European Equities: Finding Durable Growth Beyond the AI Trade

29 September 2026
4 min read

As Europe’s growth story broadens, compelling opportunities are surfacing in overlooked areas.

Investors seeking growth in European equities might be discouraged by the region’s lack of technology giants, the kind of companies that have dominated US market returns in recent years amid soaring investment in the AI build-out. Yet while Europe isn’t prominent in the AI narrative, selective investors can still find attractive pockets of growth. 

Recent earnings results for European companies have been particularly strong, yet valuation multiples have compressed (Display). Earnings guidance is improving across a wider set of sectors and industries, such as industrials, financials and materials. We believe investors can find resilient growth in these areas from companies with strong profitability, driven by robust competitive advantages, management skill and capital discipline that help firms thrive in changing conditions. 

Earnings Growth Has Improved, While Valuation Multiples Have Compressed
Bar charts show five-year EPS growth rising to 16.5% by August 2026 as price/earnings multiples remain below 2024 highs.

Past performance and current analysis do not guarantee future results. 
EPS: earnings-per-share
As of August 31, 2026
Source: FactSet, MSCI and AllianceBernstein (AB)

AI Warrants a Highly Selective Approach

The AI story has continued to shape the global equity market narrative. In fact, 19 of the top 20 contributors to MSCI ACWI Growth performance during the first half of 2026 were technology stocks, and the top nine were semiconductor companies. Conversely, the top five index detractors were all software and internet-related names, which have faced pressure given their vulnerability to AI disruption. 

As speculative outlooks continue to drive up valuations in parts of the AI ecosystem, we think it’s increasingly important to stay disciplined and focus on quality. In our view, investors should seek to identify companies that are able to benefit from the clear structural growth of AI over the long term, by both accelerating revenue growth and taking cost out of the business. 

Leading European semiconductor equipment manufacturers are a good example. These companies benefit from formidable competitive advantages, dominant market positions and structural growth drivers including the commercialization of AI and migration to the cloud. Investing in these businesses enables a pick-and-shovel approach to the AI theme, focused on the extraordinary growth of capital expenditure on AI without undue exposure to the rapid underlying technology shifts. Examples include ASML and Besi, two Dutch companies that make essential components for semiconductor equipment manufacturing. 

Quality Growth Has Been Overlooked

Enthusiasm for AI has also altered how investors price quality companies, leading to unusual valuation distortions across the broader market. 

Quality companies typically trade at a premium to the broader market because investors are willing to pay more for businesses with strong profitability, competitive advantages and resilient cash flows. However, European quality growth firms with strong fundamentals haven’t been rewarded in recent years (Display) as the market leaned into speculative growth. As a result, valuation premiums of quality growth stocks compared to the broad market have compressed to the narrowest point in recent memory, meaning quality now looks inexpensive relative to the wider market. We believe investors with a long-term outlook can find quality portfolio candidates trading at especially attractive valuations across several sectors. 

Growth and Quality Have Underperformed the Most in 25 Years
Returns Have Started to Improve in Recent Months
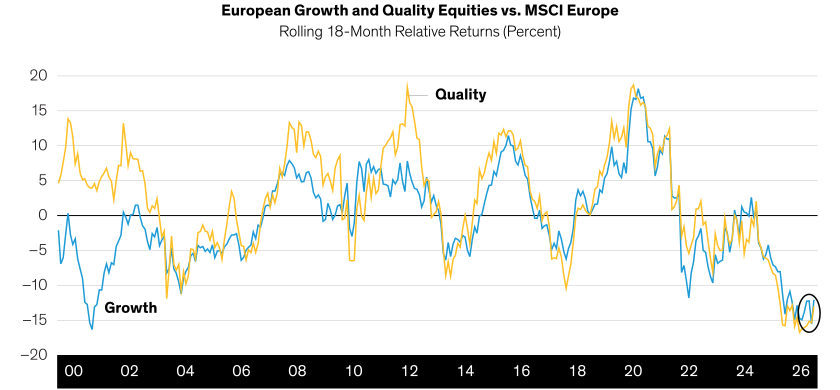
Line chart shows European growth and quality stocks deeply underperforming MSCI Europe, with a modest recent rebound.

Past performance and current analysis do not guarantee future results. 
Rolling cumulative 18-month relative returns of MSCI Europe Growth and MSCI Europe Quality versus MSCI Europe, measured monthly. 
As of August 31, 2026
Source: MSCI and AB

European Industrials Offer Multiple Growth Engines

Industrial stocks deserve attention. For a time, Europe’s industrial economy appeared to move at two speeds. AI beneficiaries and defense-linked companies enjoyed strong earnings momentum, while more traditional areas—including construction, materials, autos and capital goods—faced stagnant demand amid higher interest rates and weak manufacturing data.

Now, we’re seeing a notable acceleration elsewhere, as evidenced by solid and improving earnings results for companies with complementary engines of growth including structural organic drivers and, in some cases, a record of strategic acquisitions. In challenging market conditions, we believe this two-pronged growth model should bring some resilience. Companies following this dual approach include The Weir Group, a supplier of machinery to mining and industrial operators, and Addtech, a serial acquirer across industrial end markets. 

Companies like these have done well operationally by continuing to take market share and improve margins. In select industrial businesses, we believe a recovery in end markets could further shore up the durability of earnings growth. 

Banks Are Back in Scope 

Quality growth investors might not typically lean toward European banks, which have been burdened by negative interest rates and post-financial crisis cleanup. But since 2018, the industry has evolved, and some European lenders are showing record profitability, solid capital returns and technological leadership. 

Several factors have fueled these improvements. The shift from negative to moderately elevated interest rates by 2026 has buoyed banks’ financial performance, while the implementation of reforms has strengthened their capital positions. European banks have also embraced digital transformation, with AI enhancing efficiency and productivity—positioning the industry for long-term cost improvements despite near-term investment needs.

Specialized banks offering quality features include Standard Chartered, with a diversified international footprint and exposure to high-growth markets in Asia and the Middle East. Italy-based FinecoBank stands out among European wealth platforms for its technology-led, digitally focused model and its significant share of Italy’s exchange-traded fund trading volumes. 

Common Threads for Compounding Growth

Across all these areas of promising growth within European equity markets, common threads include cyclical improvement and differentiated business models that help companies stand out from the short-term AI-dominated narrative.  

Markets often reward what is most visible before they recognize what is most durable. That can create opportunities for investors who look beyond crowded trades and focus on high-quality European businesses with the discipline, pricing power and earnings resilience to compound growth over time.

The views expressed herein do not constitute research, investment advice or trade recommendations and do not necessarily represent the views of all AB portfolio-management teams. Views are subject to revision over time.

MSCI makes no express or implied warranties or representations, and shall have no liability whatsoever with respect to any MSCI data contained herein. The MSCI data may not be further redistributed or used as a basis for other indices or any securities or financial products. This report is not approved, reviewed or produced by MSCI.

References to specific securities discussed are for illustrative purposes only and should not to be considered recommendations by AllianceBernstein L.P. It should not be assumed that investments in the securities mentioned have necessarily been or will necessarily be profitable.


About the Authors