Equity Outlook: AI, Higher Rates Raise the Bar for Diversification

October 02 2026
7 min read

New risks reinforce the need for high-quality, complementary return drivers.

Global equities advanced in the third quarter as market returns broadened away from technology. But AI’s disruptive impact is spreading across sectors and industries—transforming the very nature of investment diversification.

The MSCI All Country World Index (ACWI) of global stocks rose by 1.6% in the third quarter, led by Japanese stocks and US large-caps (Display). Chinese stocks tumbled, weighing on emerging markets (EM), which lost some of their earlier momentum but have still notched strong gains year to date.

Japan and US Large-Caps Led Global Gains While China, EM Underperformed

Past performance does not guarantee future results.
EM: emerging markets. *Japan represented by MSCI Japan, US large-caps represented by S&P 500, UK represented by MSCI United Kingdom Index, Australia represented by MSCI Australia Index, emerging markets represented by MSCI Emerging Markets Index, Europe ex-UK represented by MSCI Europe ex-UK Index, US small-caps represented by Russell 2000 Index and China represented by MSCI China A Index.
As of September 30, 2026. Source: FactSet, FTSE Russell, MSCI, S&P and AllianceBernstein (AB)
During the quarter, persistent inflation and renewed monetary tightening prompted a spike in bond yields, increasing pressure on valuations and cash flows. Together with AI’s expanding influence, we believe the higher-rate backdrop is sharpening the need to find sources of differentiated returns.

Value Stocks Fueled by Energy Surge

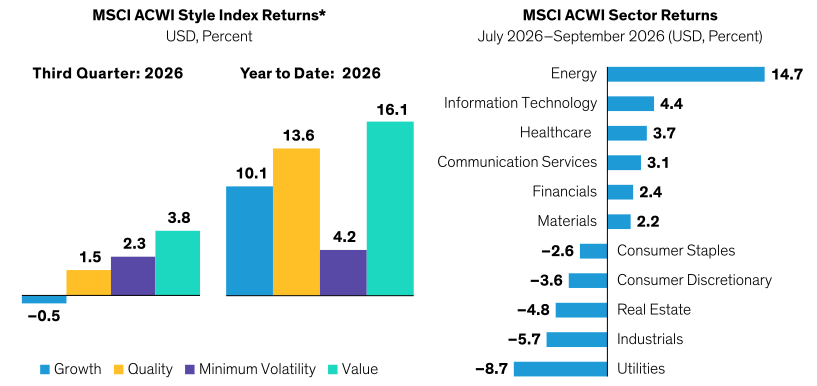
Style returns reflected shifting market patterns. As leadership broadened beyond mega-cap growth stocks, value stocks outperformed. The MSCI ACWI Value Index rose by 3.8% in the quarter and 16.1% on the year (Display).

*Growth represented by the MSCI ACWI Growth Index.
Quality represented by the MSCI ACWI Quality Index. Minimum Volatility represented by the MSCI ACWI Minimum Volatility Index. Value represented by the MSCI ACWI Value Index.
As of September 30, 2026.
Source: FactSet, MSCI and AB

Energy stocks surged, outpacing all other sectors by a large margin behind rising global demand and Middle East supply constraints. Healthcare and materials also did well, while technology gains slowed—even as AI continued to dominate headlines.

Tech Turbulence Signals Shift

Volatility across the tech sector—and in semiconductors in particular—jumped in the third quarter to its highest levels since the dot-com crash of the early 2000s (Display). We believe much of the volatility reflected headline risk and unease about the pace of hyperscaler spending, rather than any material deterioration in technology fundamentals. During the quarter, we also saw wide dispersion in the Magnificent Seven stocks. Semiconductor stocks told a similar story: US chipmakers staged a late-quarter rally, while the memory-chip-heavy South Korean Kospi Index came under intense pressure in July.

Tech Volatility Reaches Its Highest Since the Dot-Com Crash
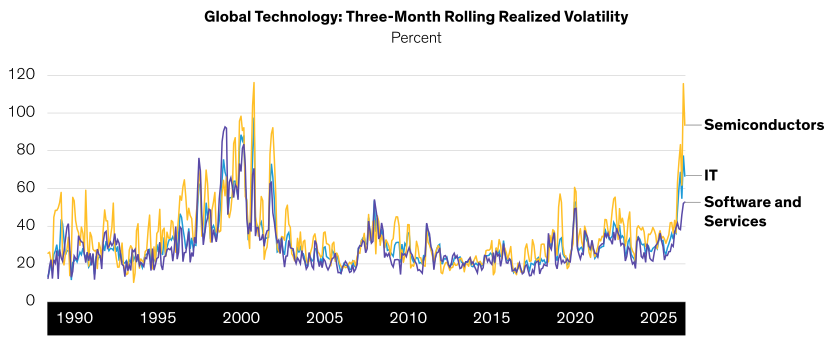
Line chart shows three-month realized volatility of IT stocks, semiconductor stocks and software/services stocks.

Past performance and current analysis does not guarantee future results.
Three-month rolling realized volatility from month-end prices (annualized). Market capitalization > $5 billion. Based on median company data for global industry groups.
As of August 31, 2026
Source: UBS HOLT and AllianceBernstein (AB)

AI: The Everything Trade?

At first glance, increased tech-sector turbulence appears to challenge the dominant AI-driven narrative. High market concentration has often fostered an all-or-nothing mentality, with large technology stalwarts either dominating the broader market or beating a hasty retreat. Until recently, there’s been little in between.

But the third quarter could mark a shift from AI enthusiasm to AI execution. Investors are increasingly questioning whether massive investments in AI infrastructure can be converted to profits down the road.

AI is also starting to power a growing share of the global economy. Companies across industries are exploring ways to turn AI adoption into productivity gains and innovative business models. AI’s influence now extends well beyond energy infrastructure and data centers to include semiconductors and semiconductor equipment, machinery, and construction. Meanwhile, software stocks have decoupled from AI-enablers on fears that their historically strong moats are vulnerable. The result is an increasingly complex ecosystem.

The distinction between investment speculation and tangible productivity benefits will be critical for identifying business models that can create durable value from AI. Put another way, investors may no longer be able to choose between AI exposure on one hand and broad-based diversification on the other. Instead, we believe thoughtful AI exposure should be paired with complementary return sources to avoid risky binary trades on a single, disruptive theme.

Diversification Is Harder to Find

Yet just as diversification has become more urgent, AI’s growing influence could make it harder to achieve.

Historically, investors could spread their assets across sectors, investment styles and asset classes to achieve a balanced portfolio. But today, the scale of AI-fueled capital spending is intertwining assets that previously moved more independently. At the same time, not all stocks that seem to be AI-linked are trading together as might be expected. In this environment, we believe traditional forms of cross-asset diversification provide less protection than in the past.

AI Creates New Clusters of Stocks

Cluster analysis, which shows how groups of stocks are correlated, can help illuminate how relationships among AI, energy, semiconductors and software stocks are evolving.

We analyzed the evolution of a broad basket of global AI-related stocks since late 2023 and found a growing set of companies and industries have been pulled into the group (Display). Initially, we identified 68 stocks and 15 industries as part of the cluster that tended to exhibit similar trading patterns in December 2023. Tracking its progression over the next three years, our research found that more stocks and industries have become associated with the AI build-out. More importantly, the stocks in the AI group are now more than twice as volatile as the market, reflected by a beta greater than 2.

AI Is Pulling More Stocks and Industries Into Its Orbit
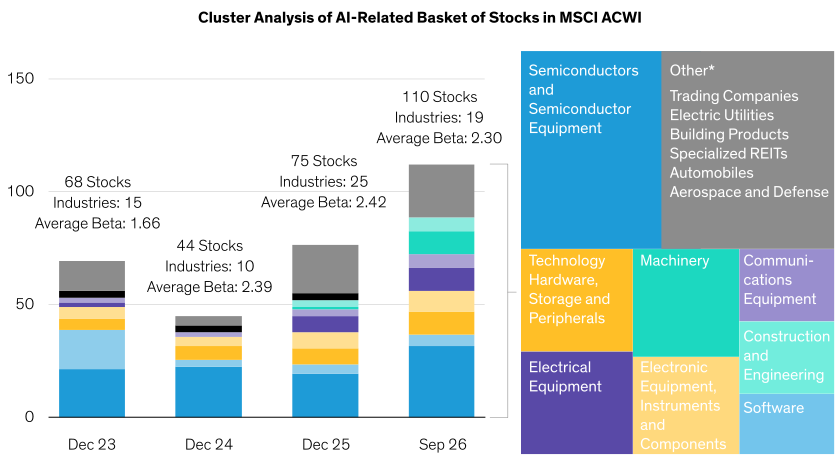
Segmented bar chart illustrates a cluster analysis of AI-Related basket of stocks in MSCI ACWI over the last three years, with a treemap diagram breaking out the diverse industries in the current AI-related cluster.

Historical analysis does not guarantee future results.
REITs: real estate investment trusts
Clusters are identified using AB’s proprietary stock-clustering framework, which groups stocks exhibiting similar trading characteristics. The AI-related cluster shown represents the principal cluster containing the largest share of AI-exposed companies in each period.
*Select industries among 11 listed in “other” category.
As of September 22, 2026
Source: Bloomberg, MSCI and AB

Other parts of the AI ecosystem are moving to a different beat. By 2024, our research found that software stocks formed an entirely separate group, while several large consumer and advertising platforms traded more closely with businesses influenced by consumer spending and interest rates. Asian chip and memory producers also remained distinct from their US-listed peers. As we see it, these patterns suggest AI exposure now encompasses several distinct investment drivers, creating both concentration risks—and opportunities to diversify globally.

Active managers must constantly reevaluate how exposures interact. In our view, finding distinct sources of equity returns requires rigorous fundamental analysis to understand what’s driving performance and to assess the range of possible outcomes.

Uncorrelated Returns: From Emerging Markets to Value

The size and volatility of the AI complex are impacting global return patterns. Our research suggests that US and EM Asian stocks have become highly correlated with AI-related equities over the last two years. However, other EMs as well as European and Japanese stocks are less correlated with the AI trade (Display).

Which Regions and Sectors Offer Diversification to AI Exposure?
Two horizontal bar charts break out regional and sector equity correlations with the GS US Broad AI Index, highlighting areas that are more and less tied to the AI trade.

Historical analysis does not guarantee future results.
EM: emerging markets
Left display: correlation of MSCI ACWI and MSCI regional indices vs. the GS US Broad AI index. Right display: correlation of MSCI ACWI sectors indices vs. the GS US Broad AI index. The GS US Broad AI basket consists of US-listed companies that are pursuing the development of AI across all categories: hyperscalers, data center infrastructure, equipment suppliers, power and commodities.
Based on monthly returns in USD terms from January 1, 2025, through September 29, 2026.
Source: Bloomberg, MSCI and AB

These trends reinforce the need for regional diversification—with an eye on AI. While parts of the emerging markets—notably South Korean equities—are being driven by a small cohort of semiconductor and memory stocks, the broader EM landscape offers strong fundamentals and opportunities beyond AI that are less correlated with US markets. Similarly, in Europe, we believe quality growth stocks look attractive, with new opportunities surfacing in sectors such as industrials and financials.

Value stocks also offer exposure to industries that are more insulated from AI disruption—from aircraft manufacturing to agriculture—and a source of differentiated return potential. Several catalysts, including energy, increased defense spending and AI-driven capex across asset-heavy industries, have fueled value’s recent recovery. Rising interest rates could provide another catalyst for value stocks with shorter-duration cash flows.

Small-cap stocks also deserve attention. Despite a difficult third quarter, US small-caps have performed well year to date, supported by a broad-based earnings recovery. We believe smaller companies may also meaningfully benefit from AI adoption while offering lower correlation to the dominant AI trade than larger growth companies. This is because hyperscalers are spending free cash flow on AI capex, while select small-caps are well positioned to convert AI-driven productivity into cash.

Investors can also pursue diversification through portfolio design. We believe exposure to higher-risk AI beneficiaries can be balanced with defensive equity portfolios designed to cushion volatility, or with core strategies that seek lower tracking error. Quality companies play an important role in both approaches.

Rising Rates Sharpen Focus on Cash Flows

The higher rate environment makes the diversification challenge more acute. By quarter-end, a bond-market sell-off had pushed the average yield on global government debt to nearly 4%, its highest level since 2007, according to Bloomberg. In mid-September, persistent inflation prompted the Federal Reserve to raise policy rates by 25 basis points, while other major central banks are once again in tightening mode. US Treasury bond yields are unlikely to ease soon, given strong expectations for US growth and the rising debt burden.

A higher cost of capital has important implications for equity investors. When discount rates rise, markets tend to place greater emphasis on free cash flow, valuation and the durability of future earnings. Companies that consistently generate cash have greater flexibility to invest, return capital to shareholders and weather periods of economic uncertainty. Conversely, firms with weak free cash flow may struggle to sustain long-term earnings growth.

Mispriced Quality Stocks Are Worth a Look

Against this backdrop, we believe the key is finding quality companies capable of generating durable long-term returns above their cost of capital. Such businesses can be found in an array of industries, while earnings growth is more broadly distributed than headlines might suggest. This makes a compelling case for overlooked companies with durable business models, strong balance sheets, recurring revenue streams and strong cash flows.

Healthcare is a good example. The sector has historically exhibited relatively low correlation to the core AI trade but is a clear beneficiary of AI adoption. In our view, other attractive clusters with low correlations to AI include energy and chemicals as well as select financials and industrial firms.

Finding Balance in a Fluid Market

The past quarter offered an important reminder that markets are rarely as straightforward as dominant narratives suggest. We believe long-term investment success now hinges on finding attractively valued companies that can benefit from developments in AI while staying relatively insulated from crowded and risky AI trades. Diversification may be getting harder to find—but that only makes it more valuable.

The views expressed herein do not constitute research, investment advice or trade recommendations and do not necessarily represent the views of all AB portfolio-management teams. Views are subject to revision over time.

MSCI makes no express or implied warranties or representations, and shall have no liability whatsoever with respect to any MSCI data contained herein. The MSCI data may not be further redistributed or used as a basis for other indices or any securities or financial products. This report is not approved, reviewed or produced by MSCI.


About the Authors